

From yield-bearing collateral to bitcoin-backed credit score, the inaugural version of The Way forward for Capital Markets explored how bitcoin and tokenised property are evolving into the foundations of a extra environment friendly, accessible and interconnected international monetary system.
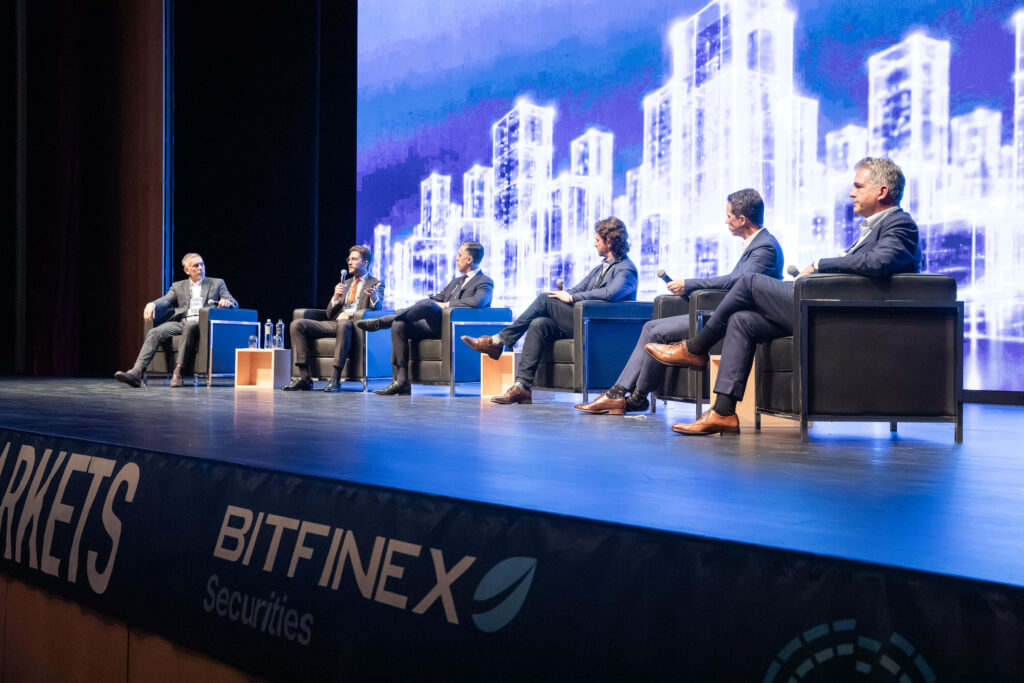
Bitfinex Securities Head of Operations, Jesse Knutson moderates the dialogue on bitcoin treasury firms.
The tokenised asset market has grown right into a multibillion-dollar business over the previous decade, attracting a number of the world’s largest monetary establishments. But in contrast with the dimensions of world capital markets, it nonetheless barely registers.
Talking on the inaugural version of The Way forward for Capital Markets in Lugano, Switzerland, on 22 October, Adam Lawrence, co-founder and CEO of RWA.xyz, estimated the present worth of tokenised property on-chain at between $30 billion and $40 billion. Within the context of world finance, he noticed, that determine “successfully rounds to zero”.
The commentary captured each the dimensions of the chance and a central theme operating by way of the day: the following section of tokenised capital markets will probably be decided much less by the variety of property tokenised than by the financial worth they will ship.
Co-hosted by Bitfinex Securities and Blockstream Capital Companions, the occasion introduced collectively asset managers, bitcoin treasury firms, monetary establishments, regulators and infrastructure suppliers from all over the world.
Throughout ten panels, the dialog moved from the sensible makes use of of tokenisation to the rising vary of funding and financing constructions being constructed round bitcoin because it turns into more and more embedded in international finance.
Tokenisation has to do greater than characterize an asset
RWA.xyz’s information exhibits the place tokenised capital is at present concentrated. US Treasuries lead the market, adopted by non-public credit score, whereas equities have solely lately emerged as a major class.
Lawrence distinguished between property distributed on-chain and people merely represented there. Regulated securities should rely on an issuer, providing paperwork or an official investor register. The sensible query is what traders can do with the token.
Jesse Knutson, Head of Operations at Bitfinex Securities, emphasised self-custody as an vital a part of that check. “I feel it is best to be capable of withdraw it,” he stated. “It is best to be capable of self-custody it. And for those who can’t do these issues, is it tokenisation?”
Larger management doesn’t imply unrestricted switch. Will Turner of Winston Taylor highlighted how whitelisting can enable traders to carry regulated securities in their very own wallets whereas limiting transfers to verified contributors.
Know-how can not, nonetheless, create demand for an unattractive underlying funding. As Archax CEO and co-founder Graham Rodford put it: “Tokenising one thing doesn’t make it a superb product.” Nor does steady buying and selling assure liquidity.
Martin Baumann, co-founder and managing companion of CMCC International, recognized entry, distribution and liquidity as tokenisation’s principal advantages. He pointed to the CREST and Liberty Bitcoin Accumulation (LBAF) funds as examples of a brand new distribution channel providing eligible traders smaller commitments and entry to secondary buying and selling.
The regulatory dialogue thought-about the environments in El Salvador and the Astana Worldwide Monetary Centre (AIFC), the place Bitfinex Securities operates. Giles Dixon, Head of International Regulatory Affairs at Bitfinex and Tether, argued that efficient guidelines ought to concentrate on dangers and outcomes, whereas giving issuers a route past experiments and sandboxes.
The strongest case for tokenisation subsequently lies not in placing an current product on a blockchain for its personal sake, however in enhancing how worthwhile investments are issued, distributed, held and transferred.
Yield-bearing collateral is the use case
One of many clearest use case examples of tokenisation is yield-bearing collateral.
Buying and selling companies routinely put up property as margin in opposition to derivatives positions, usually utilizing stablecoins that generate no return for the dealer. Tokenised money-market funds supply an various: collateral that may proceed incomes earnings whereas supporting buying and selling exercise.
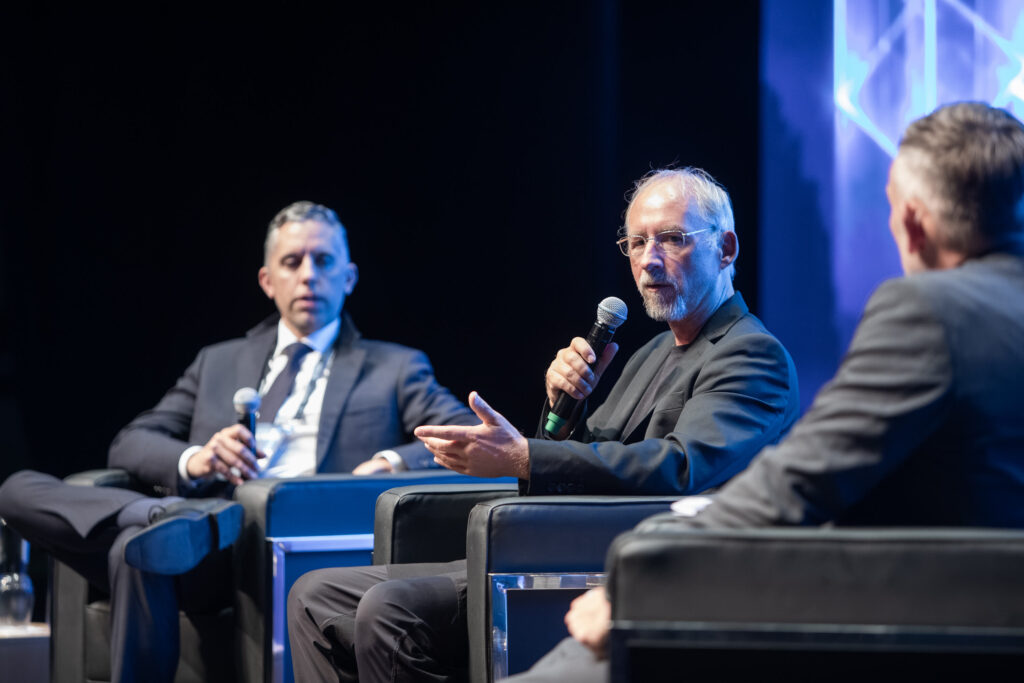
Adam Again discusses tokenised fastened earnings and collateral.
Rafael Mastroberardino of Franklin Templeton offered a dwell instance, highlighting the hedge funds and market makers at present utilizing pursuits in its Franklin OnChain U.S. Authorities Cash Fund, out there by way of the Benji platform, as collateral for buying and selling positions. The property can stay with a custodian and proceed incomes money-market yield somewhat than being transferred to an change as non-yielding margin.
Blockstream co-founder and CEO Dr. Adam Again defined why that mannequin could possibly be notably beneficial in derivatives markets. Bitcoin merchants might have little curiosity in money-market funds as standalone investments, he noticed, however they already commit substantial collateral to perpetual-futures venues. Yield-bearing devices may subsequently decrease the price of sustaining these positions.
As Lawrence put it, “Finance is about financing.” A token’s worth more and more relies on what its holder can do with it subsequent.
New monetary constructions growing round bitcoin
Past tokenisation, The Way forward for Capital Markets additionally examined how bitcoin treasury firms, income-producing securities and collateralised lending are creating new routes to institutional participation.
Tokenisation Across the World panel.
Issuing fairness at a premium to internet asset worth to purchase bitcoin turns into much less efficient when that premium narrows or disappears. That has inspired treasury firms to discover buybacks, acquisitions and most well-liked shares.
Attempt CEO Matt Cole stated the notional quantity excellent of the corporate’s SATA most well-liked shares had grown from $200 million at launch to greater than $1.4 billion in underneath a yr. Discussing institutional demand for Attempt’s most well-liked securities extra broadly, Cole stated traders confirmed little curiosity in potential bitcoin upside: “They simply wished the yield.”
Sean Invoice, co-founder and former chief technique officer of BSTR, recalled that one public pension took two years to progress from its introduction to bitcoin to a small funding. In a separate panel, Invoice stated one thought mentioned with pension funds was to put money into digital credit score and use the earnings generated to construct bitcoin publicity steadily, an method that, he stated, obtained “a fairly heat reception”.
Bitcoin-backed lending presents a unique alternative, however one nonetheless formed by the previous failures of firms akin to Celsius, BlockFi and different crypto lenders in 2022. Audio system recognized maturity mismatches, undisclosed rehypothecation and undercollateralised lending as central weaknesses within the earlier cycle.
Newer fashions emphasise segregated collateral, clear phrases and restrictions on rehypothecation. Securitisation may ultimately enable pensions and insurers to finance diversified swimming pools of bitcoin-backed loans with out originating particular person loans. Institutional adoption will rely on how these safeguards carry out underneath stress.
What comes subsequent
Discussions at The Way forward for Capital Markets pointed to an business more and more targeted on sensible outcomes, particularly higher distribution, higher investor entry and management, yield-bearing collateral and bitcoin financing constructions suited to a wider vary of mandates.
Turning these alternatives into wider adoption would require real demand and helpful secondary markets for tokenised funds. Collateral should stay legally enforceable and accessible when wanted. bitcoin-based financing constructions should in the meantime reveal that their economics are sustainable.
Lawrence’s estimate exhibits how early the market stays. Progress will finally be measured not just by the worth of property introduced on-chain, however by whether or not these property can transfer past their authentic level of issuance and be put to productive use.
For Bitfinex Securities and the broader business, the final word alternative lies in making capital extra accessible, transferable and helpful to the traders who maintain it.
Discover the tokenised securities out there by way of Bitfinex Securities.

