| Degree | Worth | Learn |
| Cycle low | $58,000 (25 June) | Retested 30 June, held by $56 |
| Weekly Open | $59,590 (29 June) | Spot trades beneath it |
| $60,000 shelf | Reclaimed, rejected | Assist flipped to resistance |
| Gamma flip | ~$68,000 | Unfavourable-gamma regime beneath |
| Mixture realised worth | ~$53,000 | Capitulation line, ~8% beneath spot |
| Month-to-month Open | $71,314 (1 June) | June closed ~18% decrease |
The clearest sign this week is what didn’t drive the transfer. Treasury yields fell, not rose: the 2-year eased from 4.24 to 4.1 % and the 10-year from 4.51 to 4.38 % between 22 and 29 June. Equities printed document highs, with the S&P 500 closing the quarter at 7,499, up virtually 10 % for the yr and posting one of the best second quarter for US indices since 2020. The greenback stayed agency, the DXY close to 101.2 after touching a 14-month excessive of 101.8 on 24 June, whereas gold slipped to $3,974 at the moment, down roughly 10 % for June.
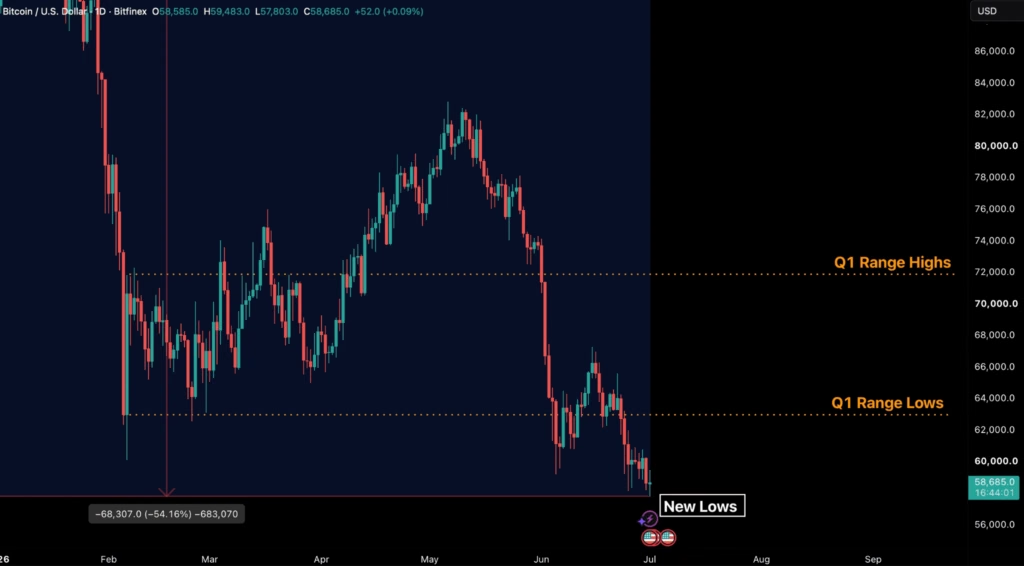
Softer yields and document equities efficiency are ordinarily a supportive backdrop for bitcoin. As a substitute BTC fell again to retest $58,000. Falling yields alongside a falling BTC is now the fourth such prevalence this cycle, and the sample is constant every time this occurs: regardless of a macro tailwind being current, BTC nonetheless declines. The sellers are largely crypto-native, which explains the breakdown in any correlation with fairness markets. This additional breaks down the correlation with fairness markets until there’s macro stress, when all danger property have a tendency to maneuver in unison.
Bitcoin just isn’t buying and selling as a risk-on proxy right here. It’s burdened by mechanical sellers as costs transfer 54 % beneath ATHs to make cycle lows at $57,803 to mark the Q3 open.
The 26 June quarterly expiry reset the choices guide however confirmed a sustained damaging gamma regime somewhat than reversing it. This was the biggest quarterly expiry of the yr and the third largest in historical past at $10.6 billion in bitcoin and ether notional, roughly 80 % of it out of the cash eliminating near 37 % of worldwide choices open curiosity. At settlement, expiring out-of-the-money gamma vanished however the partitions and flip re-formed round front-month strikes close to spot. The reset didn’t rescue the tape.
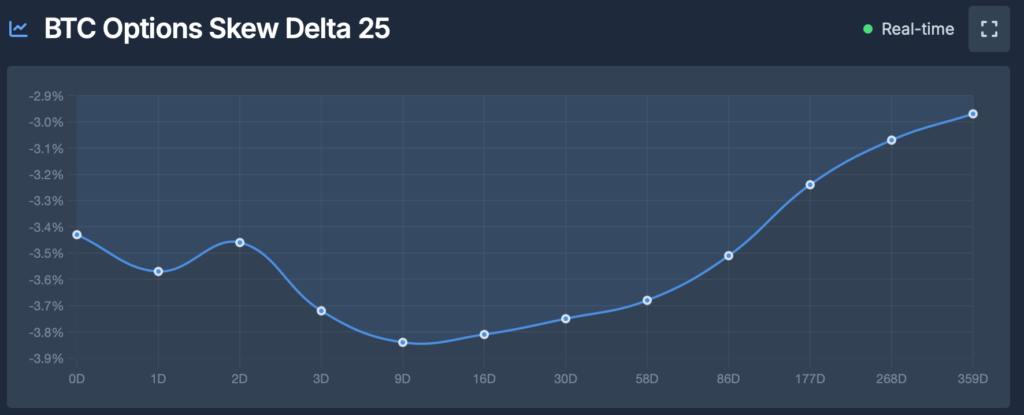
Put up-expiry, BTC nonetheless trades beneath the gamma flip close to $68,000. Beneath the flip, sellers are brief gamma and hedge with the transfer which on the spot market tape interprets to giant entities shopping for power or promoting weak spot amplifying volatility somewhat than damping it. The BTC 25-Delta Skew registers a put-dominant -5.20 % towards a call-skew of 1.50 %. This print flags as Elevated Worry: put skew sits considerably above the historic imply, confirming a structural surge in draw back safety demand throughout the guide. That is the very same sample noticed in late June which alleviated heading into expiry, however is now confirmed to be a regime somewhat than a short lived set-up that may change submit a big expiry.
The max ache that sat at $72,000 to $74,000 into expiry has remained inert. Max ache solely pins worth when sellers are lengthy gamma, and it has no gravity beneath the flip.
Funding can also be impartial and at the moment sits at roughly 2.4 % annualised, with longs paying shorts solely modestly and nowhere close to the 15 to twenty % overheated threshold seen from 14 to 18 Might, when the worth moved previous $80,000 on a reduction rally. Open curiosity on perpetuals and futures held round $45 billion, down about one % over the previous week, and no contemporary leverage has been constructed, with a lot of the deleveraging seen in early June. With the dearth of any crowded long-tail consensus positioning available in the market, we usually see slower however fixed declines as a substitute of risky strikes down.
Capital flight from institutional automobiles intensified over the previous two weeks. The seven-day rolling common for US Spot ETF internet flows plummeted to just about -$300 million per day, establishing a streak of redemptions that ranks among the many most sustained because the product’s inception. This relentless exit of capital alerts a defensive pivot from conventional market members, at the same time as BTC has misplaced the $60,000 vary lows, suggesting that present worth ranges have but to stimulate a significant reversal in institutional sentiment. Much more trigger for concern is that redemptions are led by the IBIT and FBTC ETFs, which had been the strongest ETF consumers, even in occasions of main pullbacks (in distinction to GBTC, which represents legacy holders somewhat than new capital over the previous two years.)
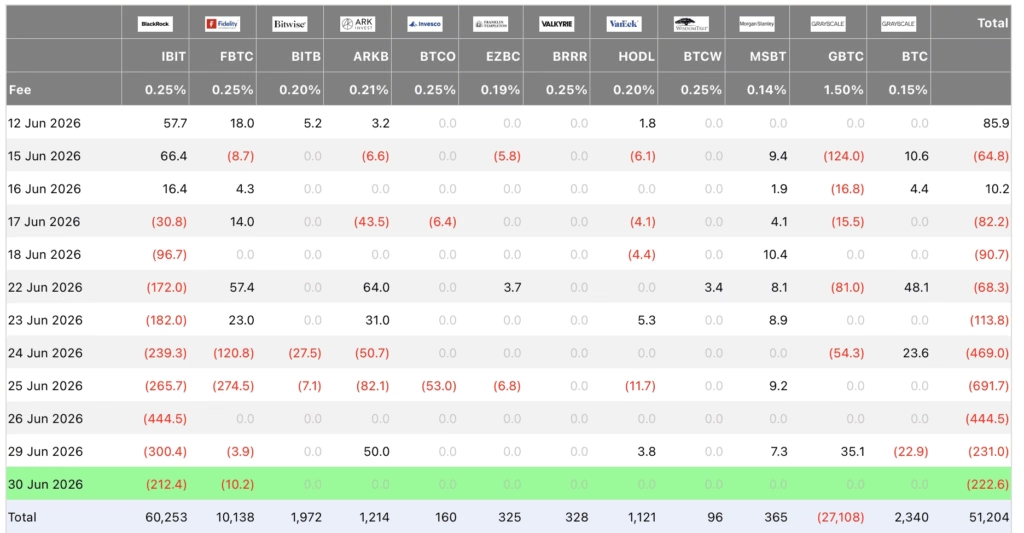
Spot ETFs posted a seventh consecutive damaging week, the longest run because the January 2024 launch. The week to 26 June noticed $1.79 billion of internet redemptions, the second-worst on document. BlackRock’s IBIT accounted for about 73 % of it; the common IBIT holder is now close to 40 % underwater.
The second vendor in ready is Technique. On 29 June its board authorised the sale of as much as $1.25 billion of Bitcoin to fund a US-dollar reserve and repair obligations: a proper path from BTC holdings to money. The STRC most well-liked dividend steps as much as 12 % from 11.5 % for document dates on and after 1 July, elevating the coupon the corporate should fund towards roughly 847,363 BTC carried at about $75,650, close to $17,000 per coin underwater. MSTR trades round 30 % beneath the worth of the Bitcoin it holds, its first sustained low cost since accumulation started in 2020. The late-Might sale of 32 BTC established that Technique will liquidate to fulfill obligations; the $1.25 billion authorisation units the ceiling on how far that may go.
We now have famous on a number of events how the 2 key spot-buyer complexes (ETFs and treasury corporations) had turned internet sellers on the similar time, and that is the crypto-native promoting motion we highlighted earlier, and which has led to a breakdown of conventional correlations. The transfer in the direction of $58,000 on $1.79 billion of contemporary outflows confirms neither has returned.
One structural consequence of the expiry issues most. The put wall that had anchored $60,000 rolled off at settlement. A rolled-off put wall means the ground should be re-established by contemporary safety or by spot demand, and neither has appeared up to now main us to imagine that the one “robust” help degree for worth is definitely a lot decrease on the realised worth and there will not be many different alerts, apart from what we will derive from orderflow and dealer positioning.
With derivatives quiet, the on-chain cost-basis construction defines the draw back.
The mixture realised worth, which is the common acquisition value of all circulating provide, sits at about $53,000. Traditionally, that is the road previous which an prolonged commerce marks full capitulation; in prior bear phases, every time the worth frolicked beneath it, these home windows proved to be the deepest of the cycle. BTC at $58,000 is sort of 9 % above that degree.
The cohort element explains why the sell-off has been orderly somewhat than panicked. The Quick-Time period Holder Market Worth to Realised Worth ratio (STH-MVRV) is round 0.83, so the marginal cohort is underwater and taking losses, however not but capitulating en masse. The Lengthy-Time period Holder Spent Output Revenue Ratio (LTH-SOPR) on a 30-day foundation is about 0.88, that means the older cohort has now additionally begun spending at a loss. The cleaning has reached long-term holders; however it has not but completed.
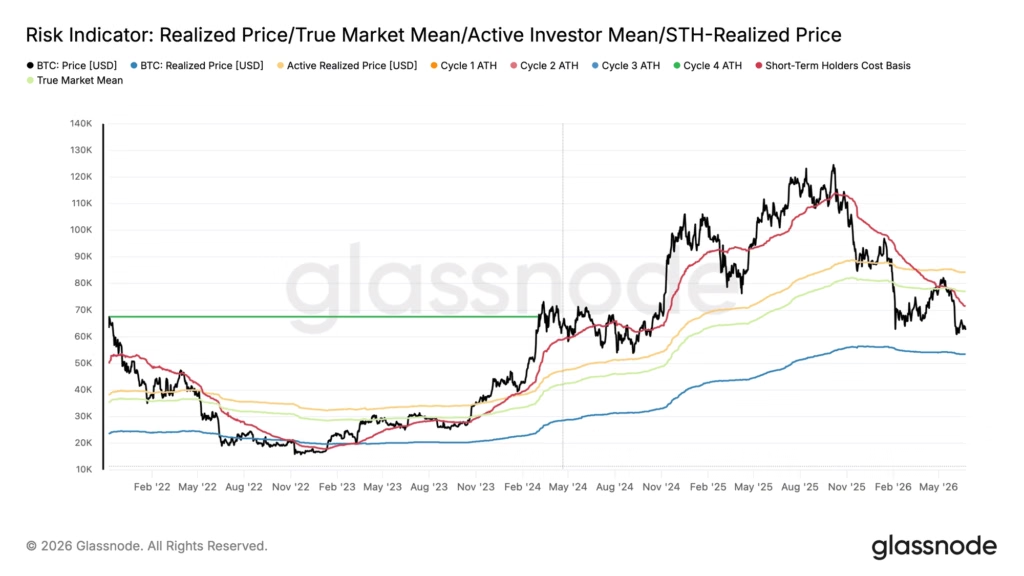
The structural counterweight stays intact. Change reserves are at a seven-year low close to 2.21 million BTC, and long-term holder provide is at a document close to 16.3 million. Cash are nonetheless leaving exchanges and ageing into affected person fingers as worth falls, with no distribution footprint from that cohort. The Month-to-month Open of $71,314 from 1 June now sits some 18 % above spot, confirming June as one of many worst months of the cycle, and the Weekly Open of $59,590 is overhead. The realised-price maintain is the strongest structural argument the bull case has. It’s help solely until the mechanical sellers enable it to be.
- The $54,000 realised-price line: day by day closes that method it take a look at whether or not it attracts bids or provides technique to the primary prolonged sub-realised-price worth transfer of the cycle.
- ETF circulation path: a real net-inflow week, not a single inexperienced day, is the primary mechanical proof the dominant vendor has paused.
- Technique execution: any submitting disclosing gross sales underneath the $1.25 billion authorisation, and STRC buying and selling relative to par into the 12 % step-up.
- Perpetual open curiosity towards worth: whether or not OI rebuilds on the lengthy aspect into any bounce, which is fragile, or the subsequent leg arrives on contemporary spot promoting.