

PowerCompute retired its bitcoin-backed mortgage in September by handing over about 267 of the 307 BTC it had pledged, and its newest SEC filings present what the small Nasdaq-listed miner seems like on the opposite facet of that commerce.
The deal reduce its secured debt by roughly 94%, to $1.25 million, and left no bitcoin pledged anyplace.
But the corporate, previously LM Funding America, now holds simply 65.7 BTC, and its quarterly report nonetheless carries a going-concern warning.
For Bitcoin buyers, probably the most helpful a part of the story is the timing: the cash have been bought close to $84,000, near the highest of the autumn vary.
The larger query is whether or not a leaner, debt-light miner can rebuild its stack from manufacturing alone.
How the Bitcoin-Backed Mortgage Was Settled
PowerCompute’s mining subsidiary borrowed about $21.89 million from Arch Lending on Aug. 25, 2026, beneath a non-recourse, collared 30-day mortgage secured by 307 BTC at 6.5% curiosity, based on its Type 10-Q for the September quarter.
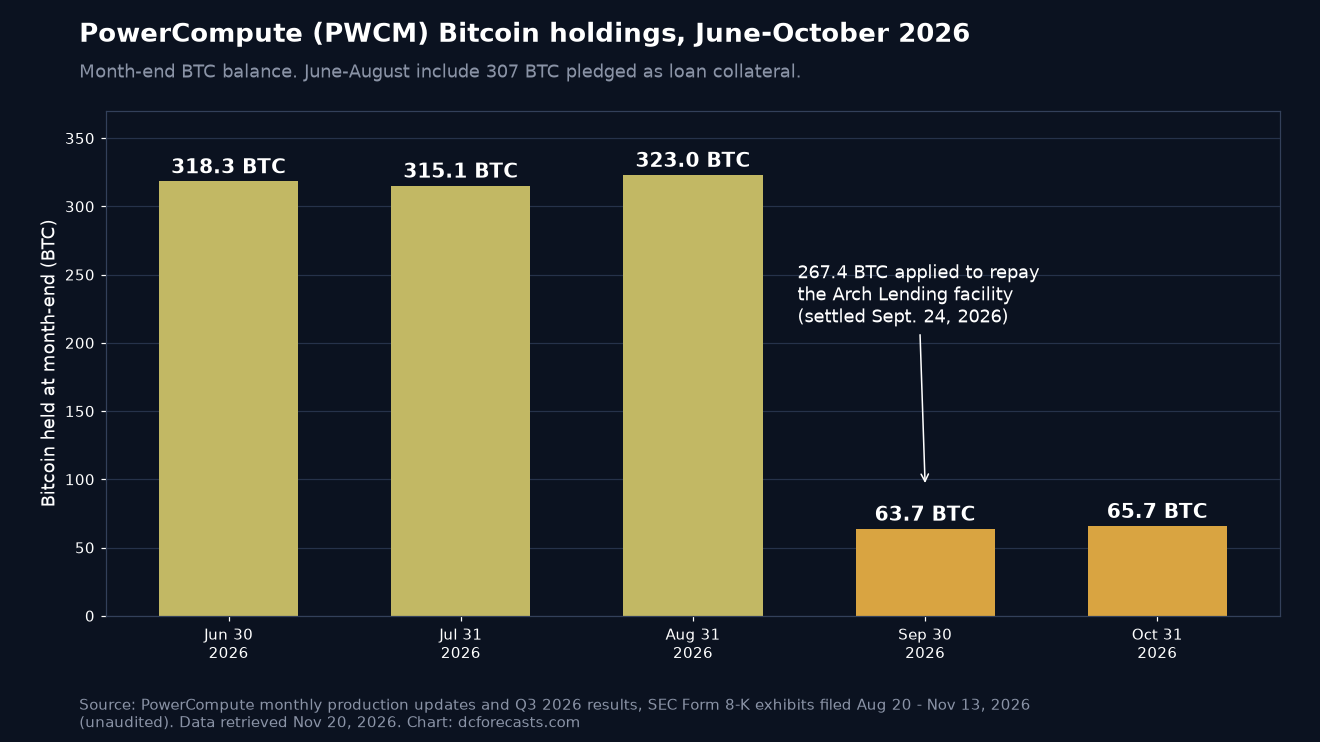
On Sept. 24, the power’s scheduled reset date, Arch bought about 267.3 of the pledged cash.
The proceeds coated $21,892,132 of principal, $118,582 of accrued curiosity and a $440,122 payment, or roughly $22.45 million in whole. About 39.6 BTC got here again to the corporate.
The corporate careworn in its Sept. 30 launch that the power had no margin-call or price-triggered liquidation provisions, and that the settlement was not a compelled sale.

ADVERTISEMENT
Easy division places the efficient value at about $84,000 per coin. Coinbase information reveals bitcoin closed Sept. 24 at $84,385.
With BTC close to $61,600 on Friday morning, the identical 267 cash would now be value about $16.5 million, nearly $6 million lower than the debt they cleared.
A Thinner Treasury, however a Cleaner Stability Sheet
The trade-off is seen within the month-to-month numbers. PowerCompute held 323.0 BTC on the finish of August and 63.7 BTC a month later.
By Oct. 31, after mining 9.0 BTC and promoting 7.0, the steadiness stood at 65.7 BTC, which the corporate valued at roughly $5.1 million, or about $2.00 per share.
The liabilities facet moved a lot additional. Complete liabilities fell to about $3.7 million at Sept. 30 from $21.6 million at June 30.
The one remaining secured debt is a $1.25 million observe whose maturity was prolonged to Dec. 31, 2027, and the corporate places annual secured curiosity at about $138,000.
We consider that’s the actual lesson of the deal. The bitcoin held its worth effectively sufficient to clear the debt in full, and the corporate exited leverage earlier than BTC slid one other 27% from the settlement-day shut.
Manufacturing Is Climbing on the Similar Energy
The working facet of the 10-Q reads higher than the headline warning.
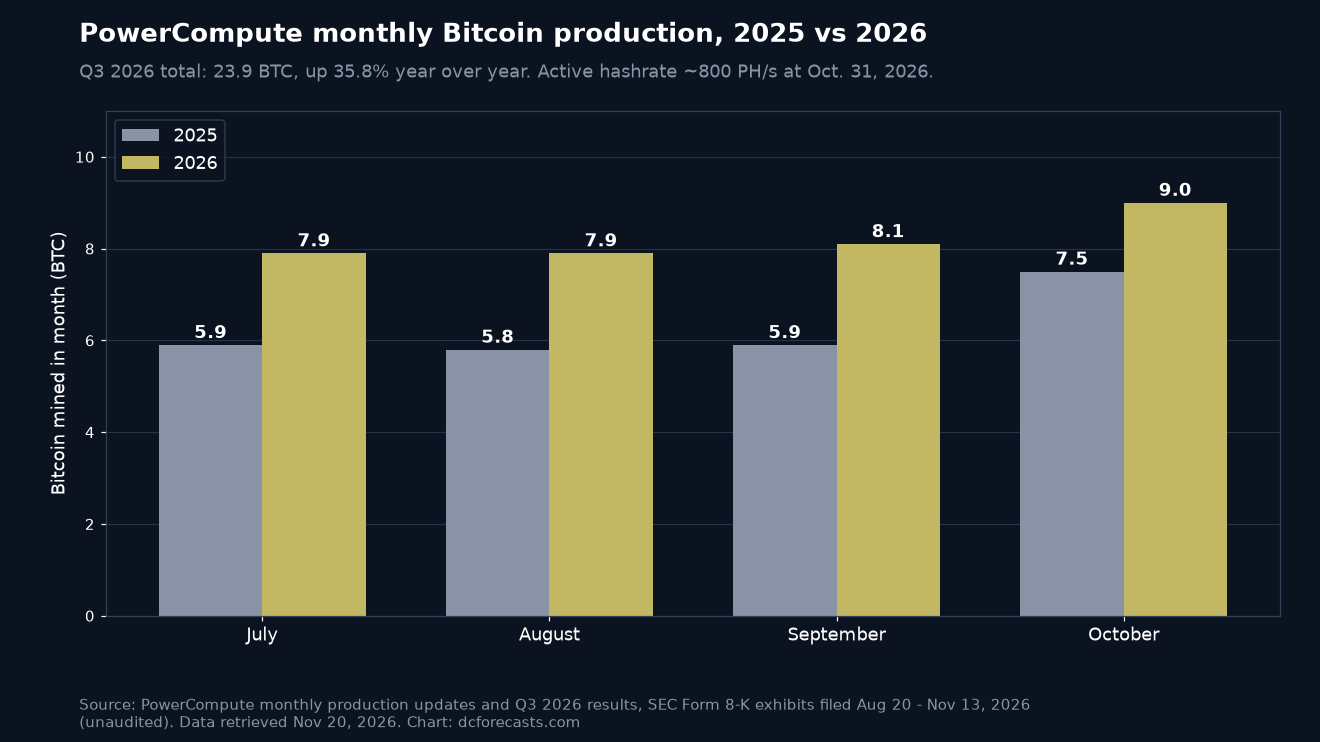
PowerCompute mined 23.9 BTC within the third quarter, up 35.8% from a 12 months earlier, and its mining margin improved to 50.7% from 29.0% within the second quarter.
The vitality value to mine one bitcoin, web of curtailment and vitality gross sales, fell to about $35,000 from about $58,000 a 12 months earlier, at a blended web energy value of about 2.4 cents per kilowatt-hour.
October output reached 9.0 BTC, up 20% 12 months over 12 months, as lively hashrate rose 11.4% to about 800 PH/s with out including a megawatt.
In November, the corporate paid about $1.0 million in money for 600 Bitmain Antminer S21++ machines. It expects them so as to add 80 to 85 PH/s, about 10% extra hashrate, as soon as deployed by mid-December.
These beneficial properties assist clarify how different miners are approaching the identical squeeze. As we coated when MARA and Riot disclosed 60,845 BTC in 2026 gross sales, the business is now buying and selling cash for energy and effectivity somewhat than holding every little thing it mines.
Why the Going-Concern Warning Stays
Money is the strain level. PowerCompute ended September with $652,628 in money, plus about $5.35 million of bitcoin and a small quantity of marketable securities.
The ten-Q states that “substantial doubt in regards to the Firm’s capability to proceed as a going concern has not been alleviated.”
Administration’s plan leans on refinancing and its at-the-market share program with Maxim Group, which had about $71.4 million of capability left at Sept. 30. The submitting warns that additional fairness financings “might have a dilutive impact on shareholders.”
Shareholders have already felt that. On Nov. 17, holders authorized a reverse inventory break up of between 1-for-2 and 1-for-10, with 757,029 votes for and 392,283 towards, based on an 8-Ok filed the subsequent day. A 1-for-25 break up took impact solely on July 13.
Market information reveals the inventory closed Thursday at about $0.40. Throughout 2,535,061 shares, that could be a market worth close to $1 million, effectively under the roughly $4 million its final reported 65.7 BTC would fetch at the moment.
That hole displays doubts in regards to the firm’s runway, not in regards to the cash on its books.
Can a Debt-Gentle Miner Rebuild Its Stack?
The subsequent checkpoints are concrete. We’d watch the November manufacturing replace, the S21++ deployment in Mississippi and whether or not bitcoin gross sales keep under month-to-month output.
Community circumstances matter too. As we famous when bitcoin mining issue dropped 9.1%, decrease issue lets the identical hashrate earn extra cash.
For us, PowerCompute is a reminder that bitcoin itself did its job. It was liquid collateral that settled $22.45 million of debt in a single day, with no margin name.
The open query is whether or not this miner can flip cheaper energy and newer machines right into a rising treasury once more. The approaching months of manufacturing information will present whether or not the comeback holds.
DC Forecasts is a pacesetter in lots of crypto information classes, striving for the best journalistic requirements and abiding by a strict set of editorial insurance policies. If you’re to supply your experience or contribute to our information web site, be at liberty to contact us at [email protected]

