

Transparency is a core a part of Go & Develop. Whereas Go & Develop doesn’t subject loans itself, it’s linked to the efficiency of Bondora Group’s underlying mortgage portfolio.
That’s the reason key portfolio statistics, together with Bondora Group’s mortgage efficiency, defaults, recoveries, portfolio high quality, and threat metrics, are vital for understanding what drives your returns.
This report brings probably the most related information collectively in a single place. So, let’s check out the numbers.
Mortgage portfolio high quality and composition
A wholesome and well-diversified portfolio helps assist extra secure efficiency, scale back focus threat, and create a stronger basis for sustainable returns over time.
Bondora manages the mortgage portfolio by way of each accountable lending selections at origination and ongoing portfolio monitoring after loans have been issued. This contains monitoring portfolio composition, compensation habits, and market-level efficiency over time.
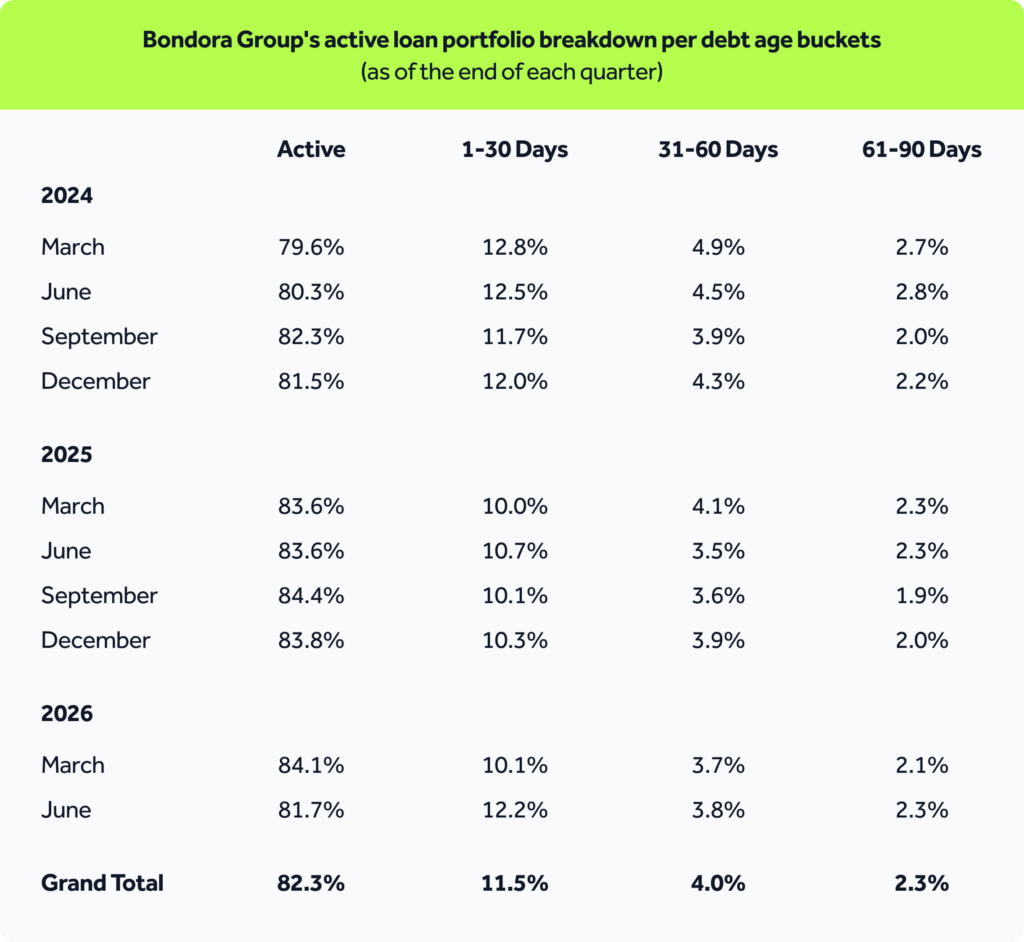
The energetic portfolio has remained persistently secure, with virtually 80% of loans remaining energetic throughout all durations. Delinquency ranges throughout totally different growing older buckets have proven solely minor variations, indicating secure portfolio efficiency throughout the noticed interval.
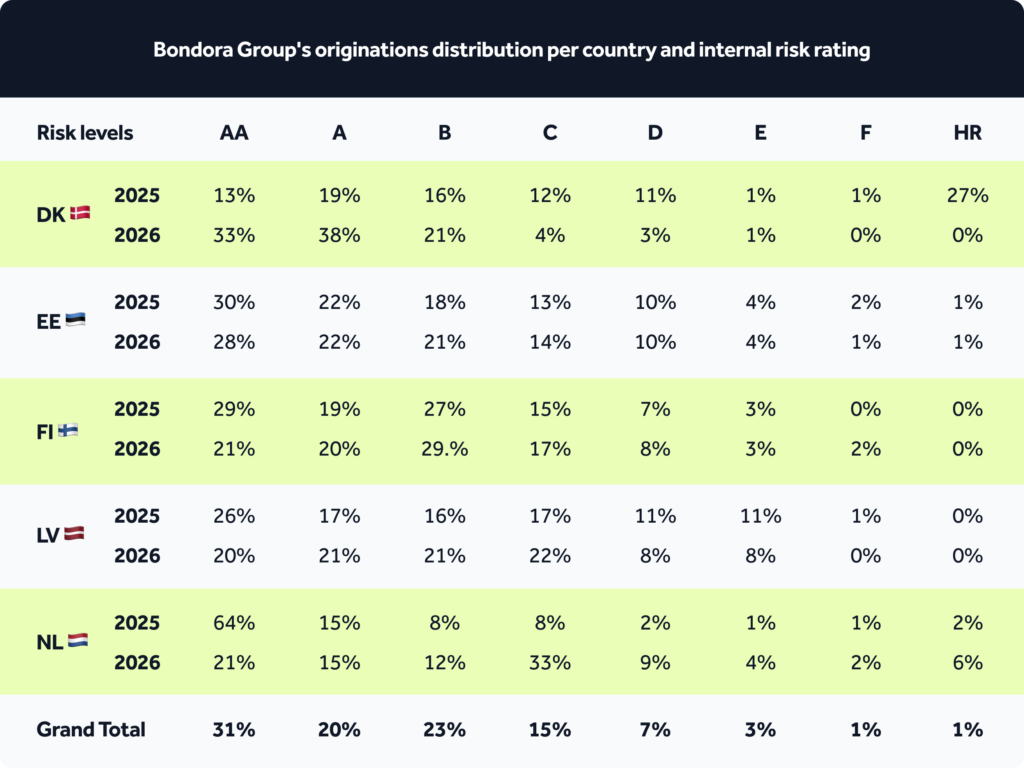
The vast majority of Bondora’s originations fall inside low-risk ranges. This displays a prudent strategy to threat administration with an rising proportion of loans within the AA-C threat classes throughout all markets.
Longer mortgage durations could make month-to-month funds extra manageable for patrons when assessed responsibly. For Bondora, mortgage time period selections are a part of the broader credit-risk evaluation and are balanced in opposition to affordability, anticipated compensation habits, and long-term portfolio efficiency.
Anticipated returns: Understanding IRR
The anticipated inner fee of return (IRR) is one metric used to evaluate the projected return potential of the mortgage portfolio.
The IRR forecast relies on a mixture of historic efficiency information and the present habits of energetic loans. Right here’s the way it works:
- IRR from beforehand issued loans is analyzed.
- Present mortgage efficiency is intently monitored, particularly key indicators equivalent to default charges throughout totally different levels of the mortgage lifecycle.
- Based mostly on this information, the anticipated efficiency of the present mortgage portfolio is projected, and the IRR is calculated.
Importantly, the forecasted IRR accounts for each anticipated defaults and recoveries. Anticipated defaults are handled as losses and anticipated recoveries are added again in as features. This provides a forecasted internet return estimate for the mortgage portfolio.
After accounting for anticipated defaults and recoveries, the forecasted IRR has remained above the Go & Develop goal return of as much as 6%* p.a. all through the previous a number of years:
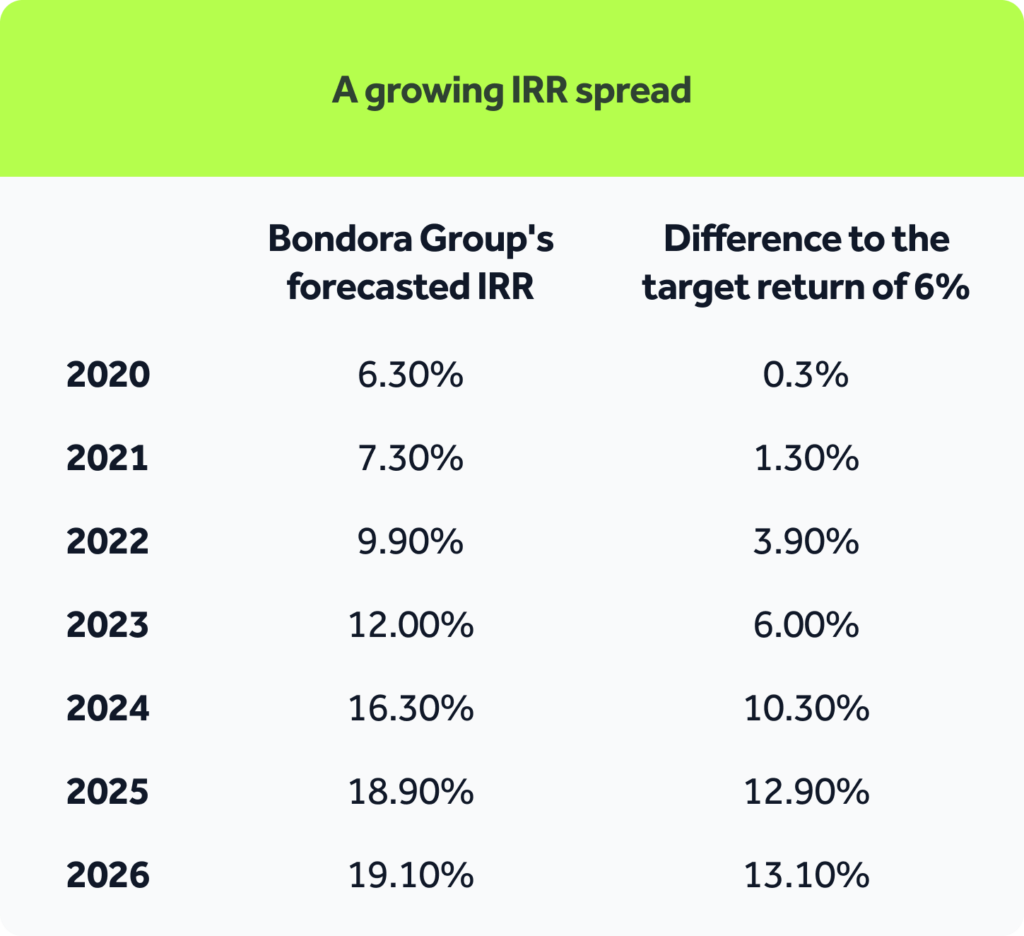
The unfold has been steadily rising, reflecting enhancements in credit score threat management and the general energy of the portfolio. These elements assist assist the long-term return mannequin behind Go & Develop, whereas liquidity administration stays a separate and vital a part of enabling near-instant entry beneath regular market situations.*
Defaults defined: What they imply and the way they’re measured
In lending, defaults are a standard a part of the mortgage lifecycle. What issues most is how they’re measured, managed, and recovered.
A mortgage is taken into account in default when funds are greater than 90 days overdue, and the client contract has been terminated resulting from arrears. A default doesn’t essentially imply the total quantity is misplaced.
Bondora begins monitoring and addressing compensation points earlier than a mortgage reaches default, from the primary indicators of fee issue. Default marks the purpose the place the mortgage strikes right into a extra structured restoration course of, with the purpose of recovering as a lot of the excellent quantity as attainable.
Restoration outcomes fluctuate by nation, and in some markets, Bondora is ready to get well as much as 70% of the defaulted quantity. For this reason defaults ought to all the time be considered along with recoveries fairly than in isolation.
On the identical time, Bondora’s purpose is to deal with each credit score buyer with respect and equity all through the restoration course of. Monetary challenges can occur, and Bondora’s restoration technique is constructed round honest, compliant, and accountable debt administration.
To higher perceive the potential affect of defaults, Bondora additionally examines Loss Given Default (LGD), which displays the remaining loss after anticipated recoveries. This helps assess the portfolio’s long-term well being.
PD12: A key threat metric
One other vital metric utilized in Bondora’s portfolio evaluation is PD12, which measures the share of loans that default inside 12 months of issuance.
PD12 helps observe how every mortgage cohort performs throughout its first yr and is among the key inputs used when calculating the forecasted IRR.
Bondora’s PD12 outcomes have steadily improved, reflecting stronger threat fashions, extra refined borrower evaluation, and continued enhancements in credit score threat management.
Along with robust restoration outcomes, a balanced threat urge for food, and the wholesome IRR unfold outlined earlier, this supplies a transparent image of long-term portfolio efficiency and ongoing enhancements in credit score threat management.
Market-specific efficiency traits
Bondora’s portfolio has developed by way of steady enchancment. Over time, stronger programs, refined threat fashions, and structured credit-risk administration have contributed to improved efficiency throughout current cohorts.
The overview under highlights chosen developments throughout Bondora’s key markets.
Observe: Q3 2025 statistics shall be accessible after Q3 2026, as soon as the total 12-month statement interval required for PD12 measurement has handed.
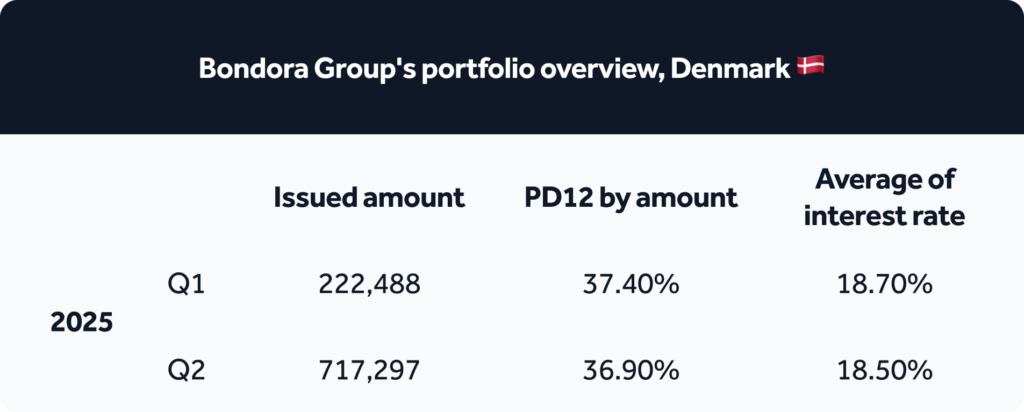
🇩🇰Denmark
- 2025: As with all early-stage market, efficiency could also be extra unstable whereas acquisition, pricing, and scoring fashions are being optimized.
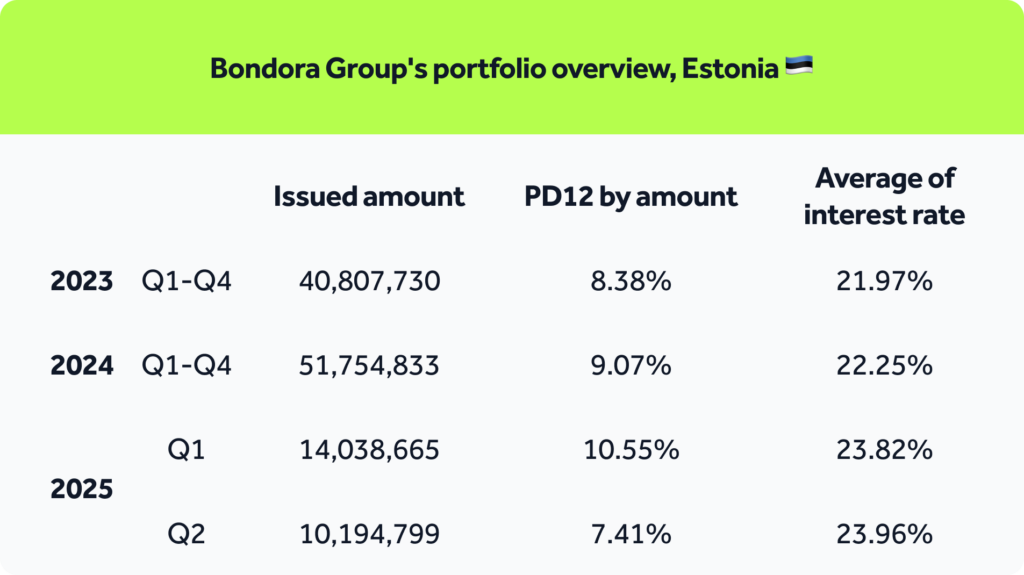
🇪🇪Estonia
- Q2 2023: Efficiency optimization contributed to the strongest unfold between rates of interest and PD12 in Estonia thus far.
- As certainly one of Bondora’s most established markets, Estonia has an extended efficiency historical past. Its key credit-risk indicators, together with PD12 and the unfold between rates of interest and default charges, have improved in contrast with earlier years.
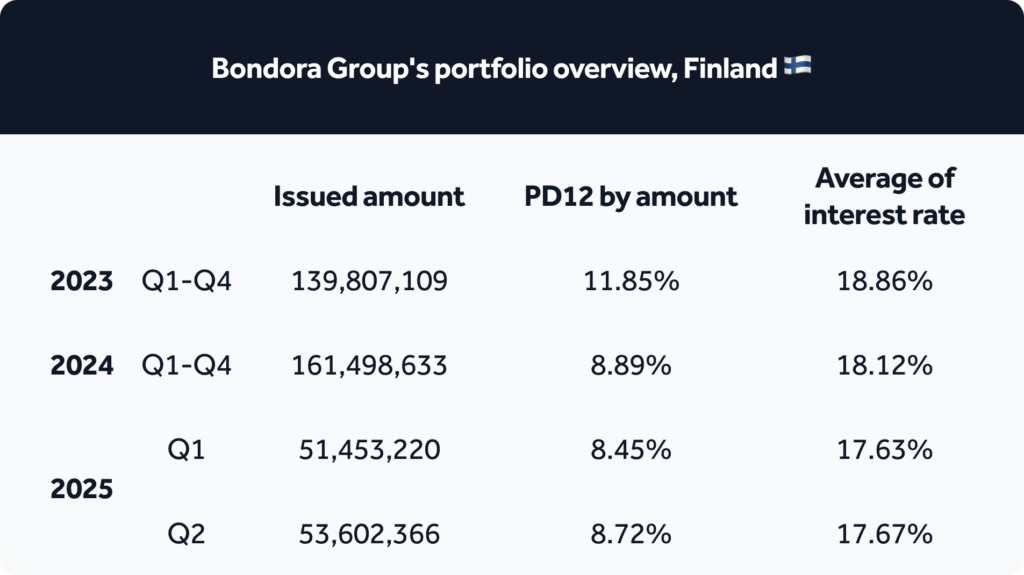
🇫🇮Finland
- Q1 2023: Efficiency quickly softened as operations have been scaled.
- Q3 2023–Q1 2024: Important enchancment when PD12 dropped from 14% to eight.3%, ensuing within the strongest unfold since market launch.
- Finland now persistently represents round 60% of Bondora’s complete portfolio, making these enhancements particularly vital for general portfolio efficiency.
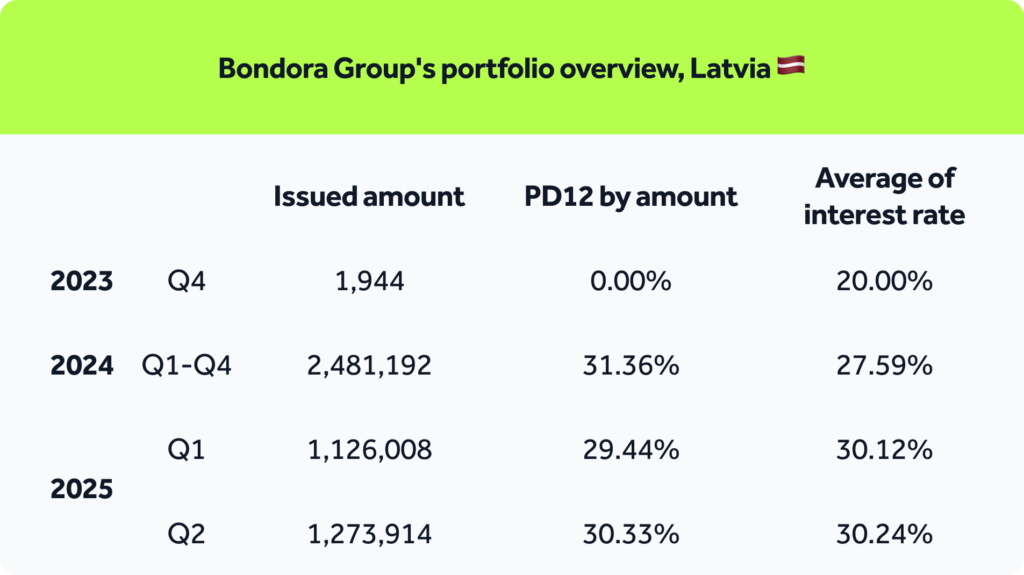
🇱🇻Latvia
- Q1 2024: As with all early-stage market, efficiency could also be extra unstable whereas acquisition, pricing, and scoring fashions are being optimized.
🇳🇱Netherlands
- Q2 2023: Bondora started scaling mortgage issuance with optimized acquisition.
- Q3 2023: The market expanded with the preliminary scoring mannequin.
- This fall 2023: Achieved the strongest risk-reward efficiency for the reason that market launch.
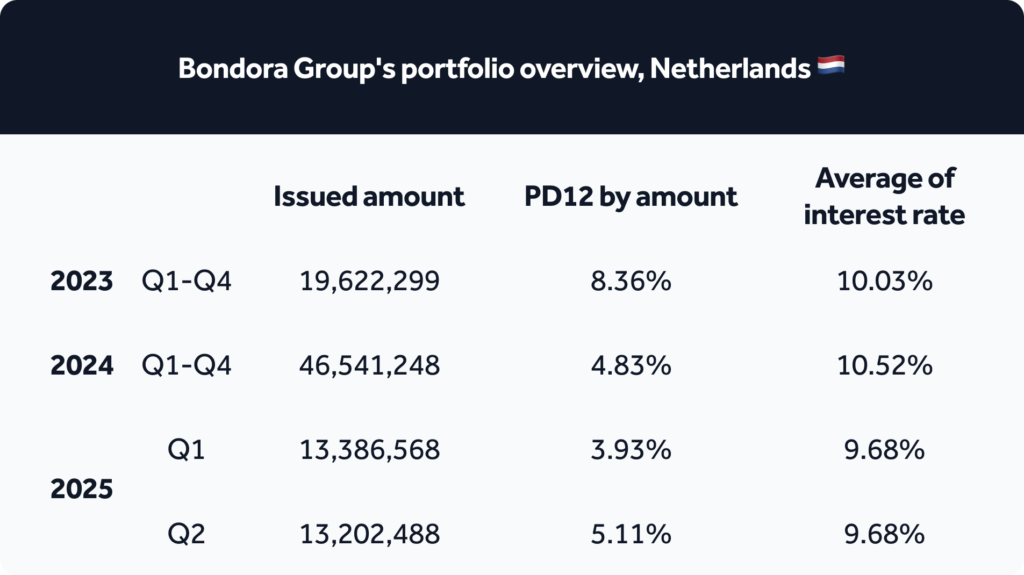
Throughout all markets, Bondora’s portfolio continues to enhance, supported by ongoing work to refine acquisition, pricing, scoring, and portfolio monitoring.
How Bondora manages mortgage recoveries
Understanding how defaults are measured is simply a part of the image. As a result of defaults are a standard a part of lending, long-term portfolio efficiency additionally depends upon what occurs after default: how successfully unpaid quantities are recovered over time.
What are typical restoration outcomes?
Earlier than diving into the method itself, let’s take a look at the outcomes. Right here’s how a lot principal is usually recovered on a €1,000 mortgage that reaches default in these markets:
- Estonia: €667
- Finland: €689
- Latvia: €667
- Netherlands: €667
These projections are based mostly on a 10-year interval and historic restoration information. In newer markets equivalent to Latvia and the Netherlands, Bondora makes use of comparable country-level information and early traits to estimate outcomes.
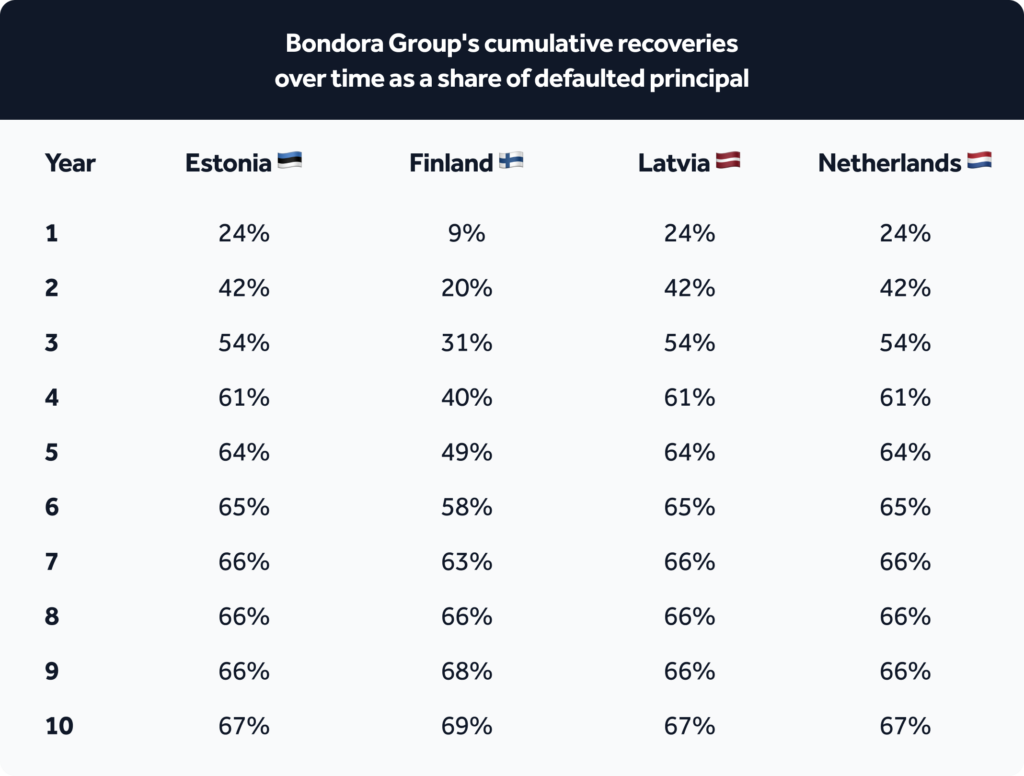
Within the first three years after default, Bondora sometimes recovers between 31% and 54% of the excellent principal, relying on the nation. These repayments accumulate steadily, yr after yr, by way of structured restoration efforts.
These figures present a helpful historic reference level, however precise outcomes could fluctuate by market, cohort, and particular person case.
Whereas authorized steps could also be a part of the method, many repayments are made by way of collaborative restoration efforts. Recoveries usually take time, which is why consistency and long-term follow-up are vital.
That’s why Bondora has developed a structured, multi-step restoration course of that delivers outcomes whereas treating each buyer with equity and respect. Learn extra about how the 4-step course of works.
How loans are at the moment distributed by stage
Right here’s a snapshot of the place defaulted loans stand within the restoration journey:
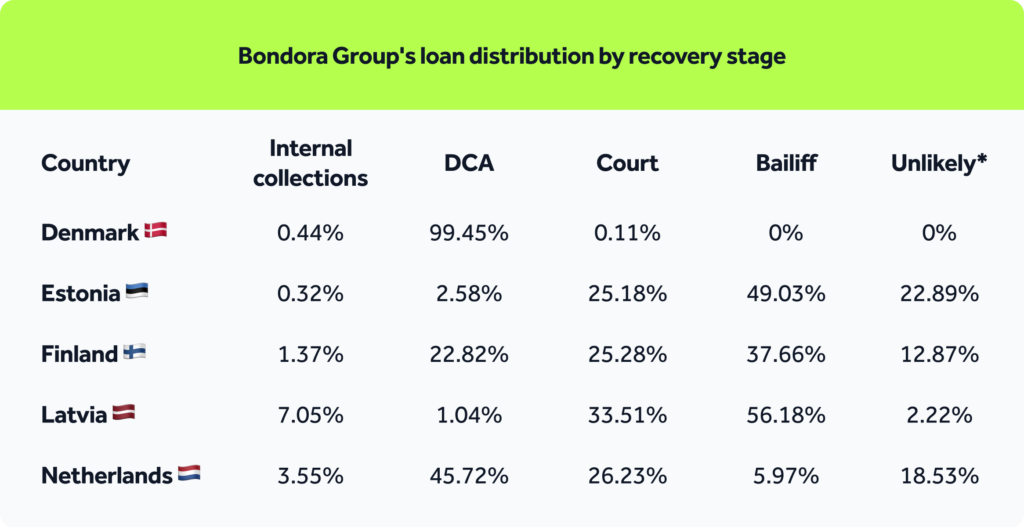
Recoveries are greater than a quantity. They replicate a structured effort to get well excellent quantities on defaulted loans, carried out respectfully and in keeping with native legal guidelines.
Bondora’s strategy helps make sure that even when defaults occur, restoration efforts proceed within the background and may assist portfolio efficiency over time.
Transparency, equity, and long-term pondering are on the coronary heart of how Bondora manages each case.
Wanting forward: Ongoing transparency and common updates
Portfolio high quality, threat metrics, defaults, and recoveries all play vital roles in understanding the efficiency behind Go & Develop. This report brings the important thing information collectively in a single place and shall be up to date over time.
For extra common updates, you possibly can discover our statistics web page and month-to-month statistics articles, the place we share the newest figures on investments, investor returns, mortgage originations, and market exercise.
Bondora Group’s audited annual monetary experiences are additionally accessible in our Assist Heart, offering a broader view of the group’s monetary efficiency.

